发布: 2024-05-263 个反向链接
商誉(goodwill)
商誉
商誉通常指没有法律保护、但因经营上的有利关系而具有社会实际价值的资产。当企业相较同业具有超额盈利能力时,超出的收益有时也会被视为商誉。商誉也可称为转让费;如果企业拥有优秀的人力资源或管理能力、较高的社会声誉和有利位置,也可以把这些无法单独表达的价值总和视为商誉。
商誉客观显现的情况通常是发生企业并购时。除此之外,即使实际上存在商誉,由于在会计上几乎难以量化和识别其价值,因此无法通过财务报表确认。
购买价款分摊
企业收购价格分摊
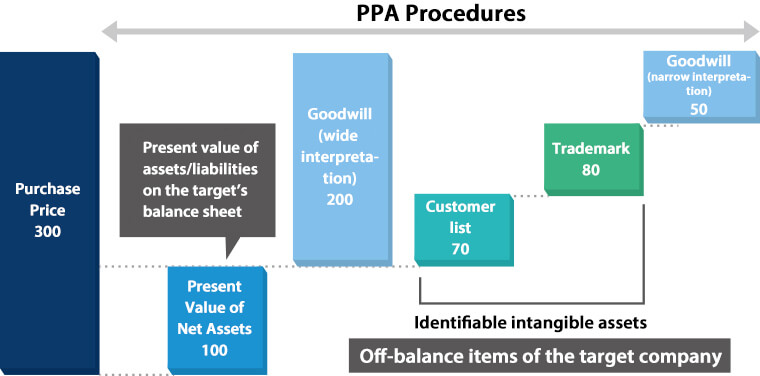
如果收购价格高于被收购企业的账面价值,就应从商誉中扣除高出的部分。(=转让费)
过程
- 首先计算企业的净资产价值
- 提高企业资产价值中被低估的部分
- 从商誉中进行摊销
示例
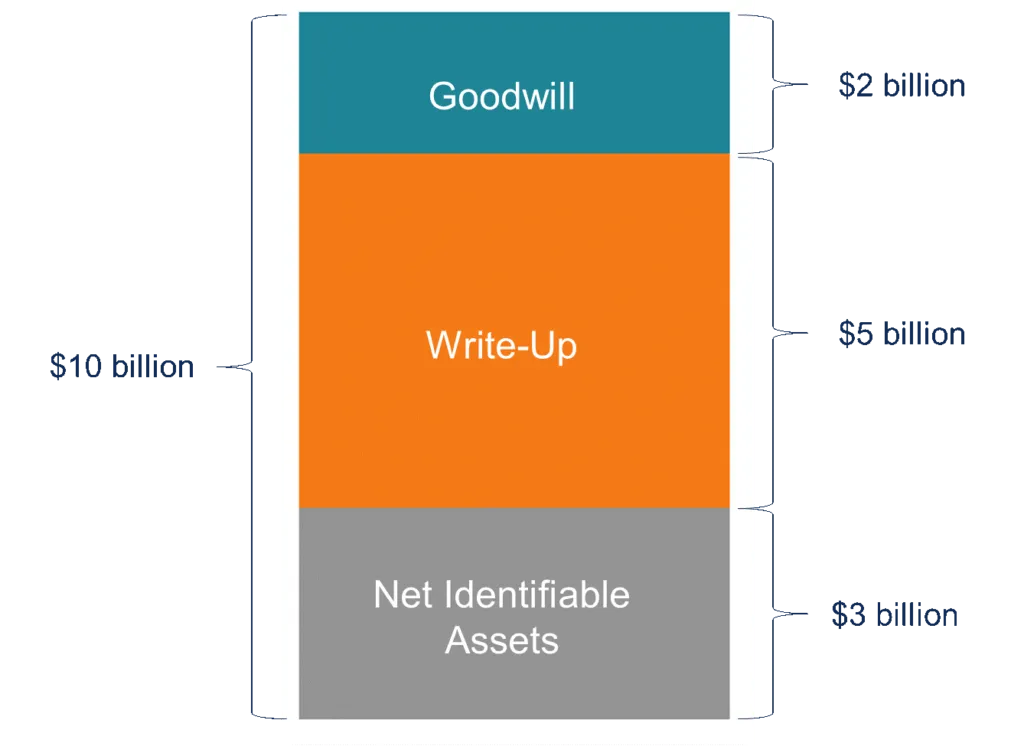
Company A recently acquired Company B for $10 billion. Following the completion of the deal, Company A, as the acquirer, must perform purchase price allocation according to existing accounting standards.

The book value of Company B’s assets is $7 billion, while the book value of the company’s liabilities is $4 billion. Therefore, the value of the net identifiable assets of Company B is $3 billion ($7 billion – $4 billion).

The assessment of an independent business valuation specialist determined that the fair value of both assets and liabilities of Company B is $8 billion. This finding implies that Company A must recognize a $5 billion write-up ($8 billion – $3 billion) to adjust the book value of the company’s assets to its fair market value.

Finally, Company A must record goodwill since the actual price paid for the acquisition ($10 billion) exceeds the sum of the net identifiable assets and write-up ($3 billion + $5 billion = $8 billion). Therefore, Company A must recognize $2 billion ($10 billion – $8 billion) as goodwill.
巴菲特的股东信中提到,按照GAAP标准最多可以在40年内摊销,这一点似乎还需要确认。
商誉减记
商誉摊销
如果收购价格高于被收购企业的资产价值,就应从企业利润中摊销相当于商誉的部分。在韩国,反之则记为廉价收购收益。